You’ve decided you need storage. You haven’t done this before, and there’s a nagging feeling that you don’t know what you don’t know yet. That’s fair. Most of what catches first-timers out isn’t carelessness, it’s assuming a generic storage-industry norm applies when Wigwam’s actual terms are more specific, and usually more generous, than the assumption.
About to book and just want the size right? Jump to sizing below. Already have contents insurance and don’t want to pay twice? Jump to the 14-day window. Planning an early or late visit? Jump to access.
The First-Timer Assumption Gap
There are three places first-time renters usually get caught out: access, insurance and sizing. All three are gaps between a reasonable default assumption and Wigwam’s actual, named term.
| Topic | What first-timers assume | What’s actually true at Wigwam |
|---|---|---|
| Access | “I can drop by whenever, it’s my stuff” | Unlimited access seven days a week, but only 6am to 10pm. Plan an early-morning or late-evening visit outside that window and you’re locked out |
| Insurance | “If it’s stolen, I’m covered” | Only if entry was forced, and only up to the value you declared. Under-declare by a fifth, and a claim pays out a fifth short, not just on the gap |
| Sizing | “I’ll just guess and adjust later” | A 25 sq ft unit takes a bed frame, desk, chair and boxes; jump to 50 sq ft for a sofa and appliances too. Getting it wrong the first time means paying for space you don’t use, or a second move |
The Access Assumption: “I Can Drop By Whenever”
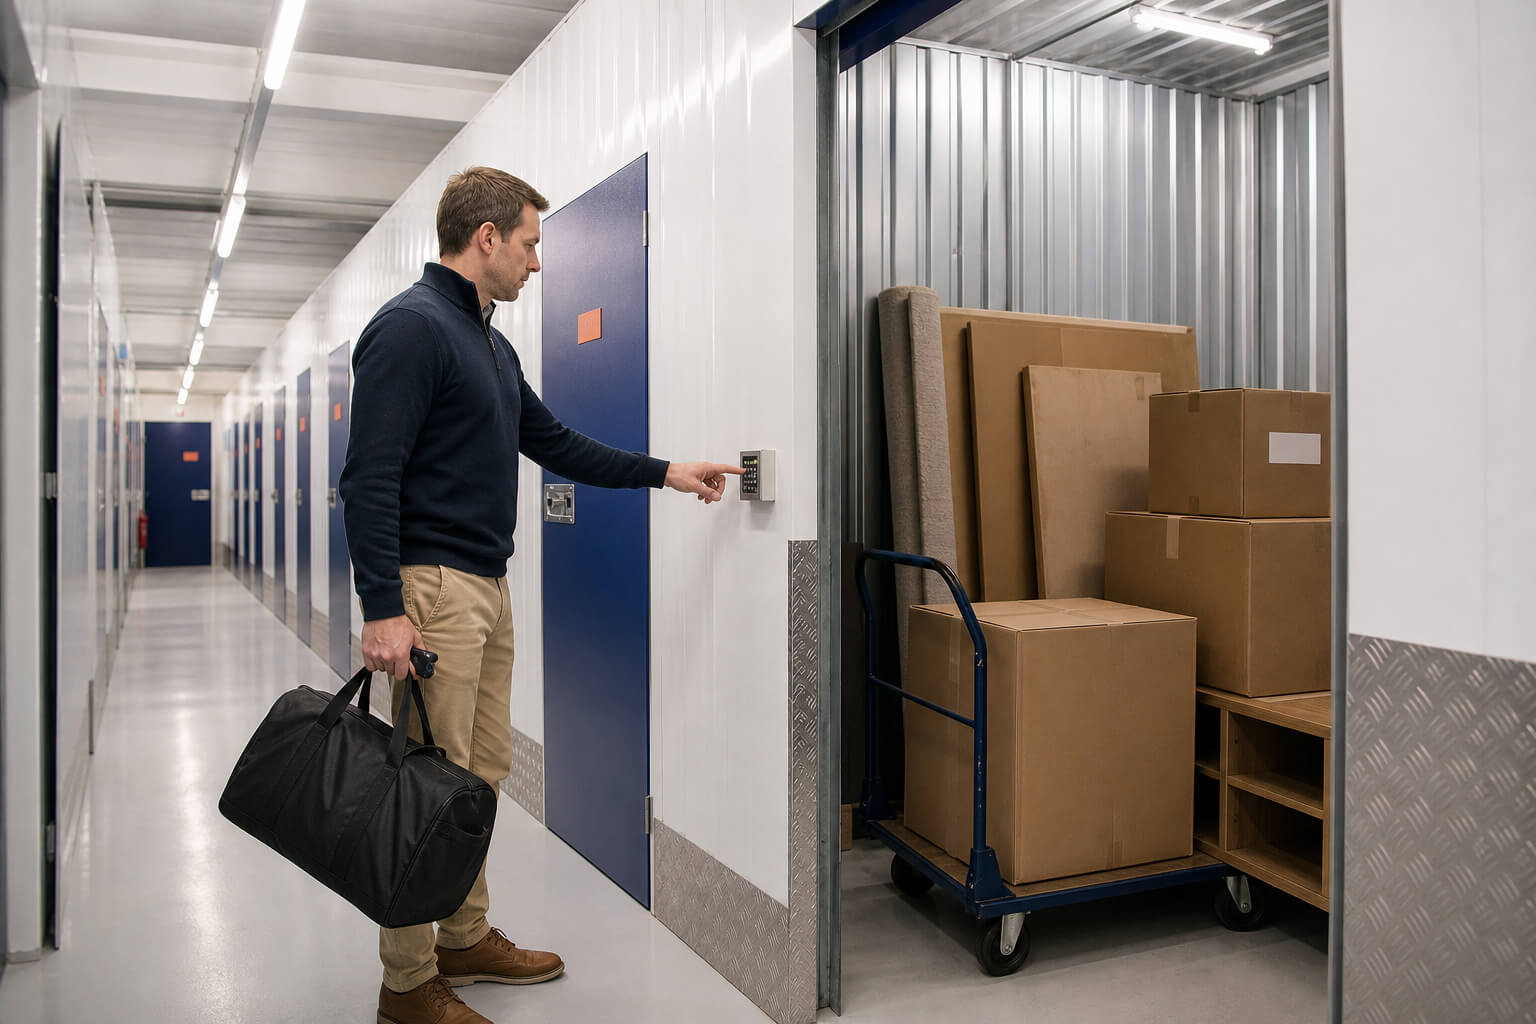
Wigwam access runs seven days a week, 6am to 10pm, not round the clock. Units are individually alarmed, and hours may vary slightly by location.
What the access window actually means for planning
If your plan involves an early-morning drop-off before work, or a late-evening dash after it, check it falls inside 6am to 10pm. Outside that window, the gate simply won’t open for you, however urgent the reason.
The minimum term and what happens when you leave
The minimum term is two weeks. When you’re ready to move out, you give the notice period stated on your Storage Agreement, normally 14 days. Once that notice period ends and the unit is vacated, any paid days you didn’t use are refunded. Those are two separate steps, the notice period and the refund, not one blurred promise.
The Insurance Assumption: “If It’s Stolen, I’m Covered”
Cover is a condition of your licence agreement, underwritten by RSA under the Self Storage Customers’ Goods scheme. Theft is covered only after forced entry, and if you’ve under-declared the value of what you’re storing, any valid claim settles proportionally to what you declared, not what it was actually worth.
What “forced entry” actually excludes
A lost padlock key, or a unit that simply wasn’t relocked properly, doesn’t count as forced entry. Without visible signs of a break-in, a claim for missing items doesn’t stand, cover or no cover. That’s a stricter test than a lot of people expect from “theft cover,” and it’s worth knowing before something goes missing, not after, when there’s nothing to be done about it.
New-for-Old and the excess
Claims settle on a New-for-Old basis. An excess applies per claim, check the current figure on the contents protection page or when you get a quote, rather than assuming a number.
Why declared value isn’t a formality
You need to declare the full replacement value of everything you’re storing, not the original purchase price, not a rough guess, the actual cost of replacing each item new today. Under-declare, and any valid claim pays out proportionally short across the board, not just on the specific items affected.
A worked example
Say a laptop and a box of tools go missing from a unit. If the lock shows signs of forced entry, and the customer declared the full replacement value of their stored goods, cover pays to replace both, minus the current excess. If there’s no sign of forced entry, the claim doesn’t stand. And if the customer under-declared their contents’ value by 20% to save on the premium, any valid claim pays out 20% short across the board, not just on the missing items. This is an illustrative scenario, not a real claim. For your specific situation, read the full contents protection terms or speak to the team before you move in.
The honest line on damp and temperature
Atmospheric or climatic damage is excluded from cover. If moisture, condensation or temperature variation damages your goods, that isn’t something the policy covers. Wigwam’s honest position is clean, dry and secure, not climate-controlled, and this exclusion is exactly where that honesty becomes financially concrete rather than just a marketing line.
When you’re ready to get a size and price sorted, the quote tool takes two minutes.
Does My Home Contents Policy Already Cover This?
A common assumption is that an existing home contents policy already covers stored goods. Many UK home policies exclude off-site storage entirely, and this usually only comes to light at claim time, when it’s too late to do anything about it. Checking before you store, not after something goes wrong, is the whole point of reading this section now rather than later.
Already Insured Yourself? The 14-Day Window
If you already have adequate cover of your own, you can prove it within 14 days of move-in for a full refund of the Contents Protection charge. Miss that window, and the charge stands regardless of what cover you actually have elsewhere.
The Sizing Assumption: “I’ll Guess and Adjust Later”
Wigwam units range from small to large, with real item-fit examples attached to each size rather than a vague “pick something roomy” suggestion.
| Unit size | What it typically holds | Best for |
|---|---|---|
| 10 sq ft | A few boxes, small furniture pieces | Overflow, seasonal items, a small archive |
| 25 sq ft | Twin mattress, bed frame, desk, chair, several boxes | A single room’s worth of contents |
| 50 sq ft | Sofa, queen bed, dresser, appliances | A one-bedroom flat |
| 100 sq ft | A full bedroom set plus significant collections | A larger move or a small business’s stock |
What actually fits at each size
The table above is a starting point, not a guarantee, since every household’s mix of furniture and boxes is different. It’s enough to self-diagnose roughly which size you’re looking at before you get a proper quote.
Why “slightly over” beats “slightly under”
Measure height as well as width and depth, since a tall wardrobe or a stack of boxes eats vertical space differently to floor space. It’s better to slightly overestimate than to guess short. Sizing wrong the first time means either paying for space you don’t use, or a second, more expensive move once you realise the unit’s too small. Because the minimum term is short and unused days are refunded, a slightly generous first booking costs little if it turns out you didn’t need all of it, a far cheaper mistake than the reverse.
A Real, Local Business: Chipping Norton, Bromsgrove and Shipston-on-Stour
This isn’t a national chain reciting generic advice, it’s three real market towns, among others, where Wigwam actually operates.
Wigwam Self Storage Chipping Norton, Wigwam Self Storage Bromsgrove and Wigwam Self Storage Shipston-on-Stour are three of Wigwam’s market-town sites, each running on the same access hours, insurance terms and size range covered above, not a watered-down version of it.
Getting It Right the First Time
Now you know the access window, the insurance mechanics and roughly what size you need. None of the three are complicated once they’re actually checked rather than assumed, which is the entire point of reading this before you book rather than after something goes wrong.
When you’re ready, the quote tool gives you a size and a price in a couple of minutes.
Frequently Asked Questions
No. Access runs 6am to 10pm, seven days a week, and may vary slightly by location.
Any valid claim settles proportionally to the value you declared, not the actual value. Under-declare by a fifth, and a claim pays out a fifth short across the board, not just on the shortfall.
Cover is a condition of your licence agreement, either Wigwam’s own RSA-backed policy or your own proven equivalent cover. If you already have your own cover, you can prove it within 14 days of move-in for a refund of the Contents Protection charge.
Around 50 sq ft typically covers a one-bedroom flat’s worth of furniture, but it depends on what you’re storing. Use the size table above as a starting point, then get an exact quote.